

TLDR: The founders who take less than the market will pay them are not leaving money on the table. They’re setting a bar they know they can clear — and increasingly, they’re finding a way to get paid the difference anyway.
The best term sheet I heard about this month wasn’t the biggest number the founder could get. It might have been the smallest.
Not because the founder couldn’t get more. Because he didn’t want it.
But what does a lower valuation have to do with getting paid now and winning in the long run?
Seed Risk at Series B Prices
Terrence Rohan said it better than I will:
The current top 5% of seed deals are the worst asset class in venture. They carry the loss ratio of a seed deal with the upside profile of a Series B.
Carta’s data backs him up.
The 95th percentile seed valuation hit $200M in 2026, up 177% year over year.
The median barely moved.
Read that again. The risk didn’t change. The price did.
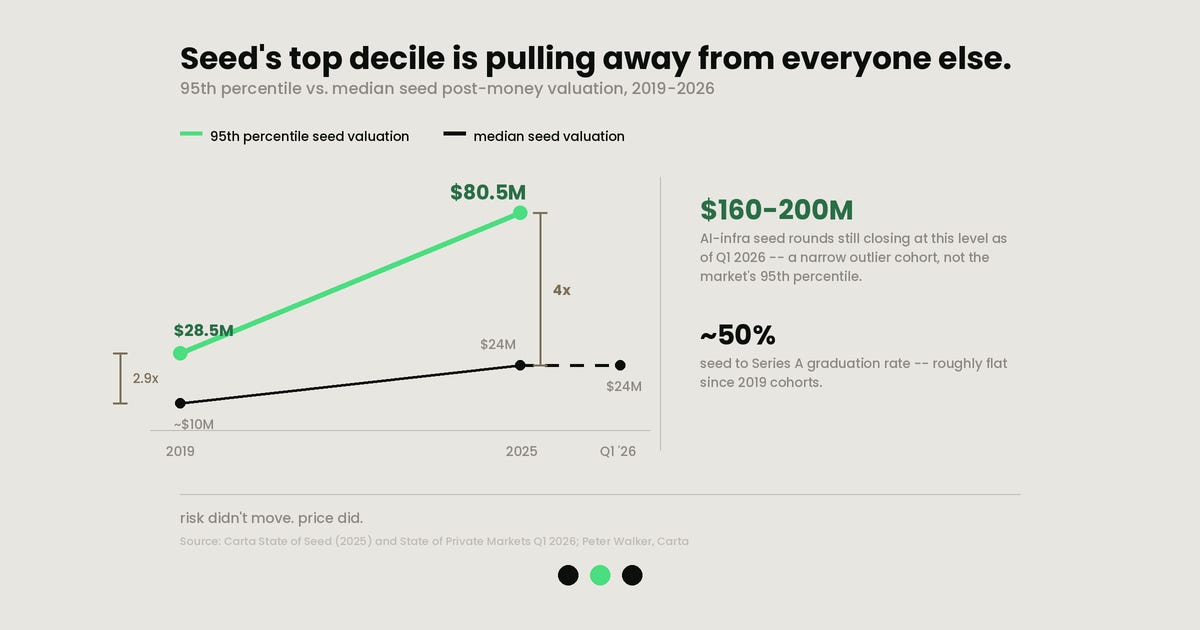
That gap is the whole essay. Somewhere between the pitch and the wire, a founder convinced a room full of professional risk-takers that a company with no revenue and eighteen months of runway should be priced like it already won. And enough of them said yes that it’s now normal.
I don’t think the founders taking that money are stupid. I think they’re playing a different game than the one that actually wins.
The Paper Wealth Trap, Again
I’ve written before about the paper wealth trap, the trillion dollars sitting in private markups nobody’s tested since 2021. Same instinct, earlier stage. A high valuation feels like winning. It’s not winning. It’s a number someone else agreed to say out loud, and now you have to live inside it.
Every hire, every board meeting, every “how’s it going” at a dinner party gets measured against that number, whether it reflects anything real or not. You didn’t earn a valuation. You inherited a bar. And most bars set that early are set by people who will never have to clear them.
What The Disciplined Founders Actually Do
I’ve seen the pattern up close a few times this year, from a few different seats:
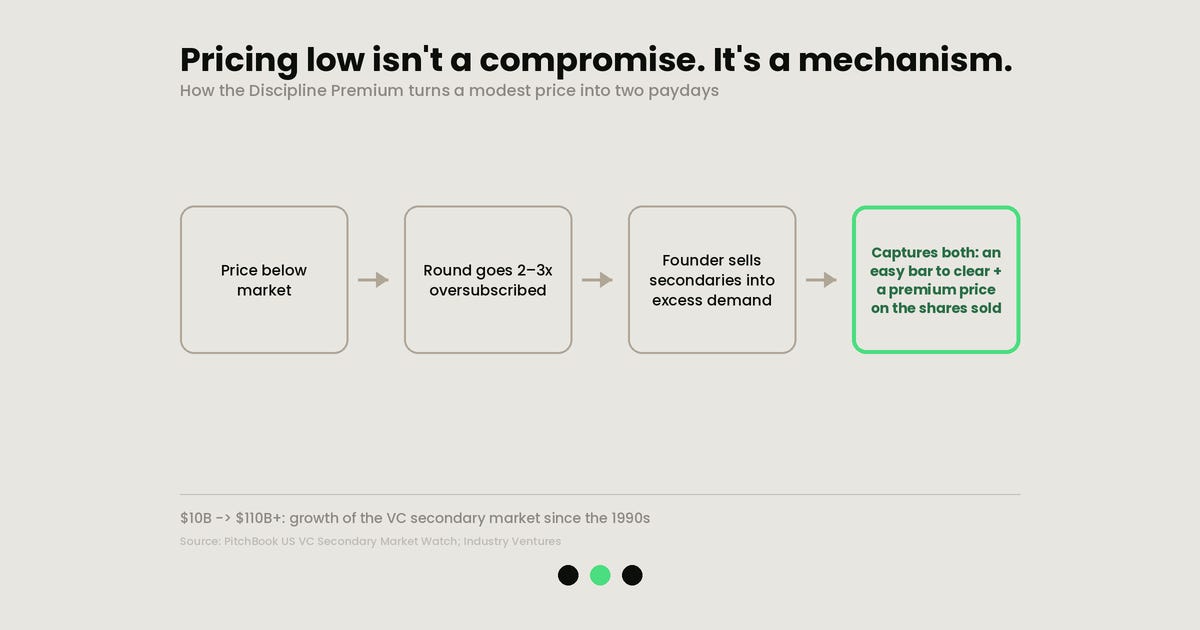
A founder picks investors for distribution and brand, at a price meaningfully below what the round would clear at auction. The round goes two, three times oversubscribed. There’s no pressure to spend the extra capital poorly, because there isn’t extra capital. The next round’s bar is something he can walk into already having cleared.
A second, unicorn watchlist founder, takes a below-market cap at seed. Then again at the A. Then again at the B. Nobody remembers the first price by the time the outcome shows up. What they remember is that every round since has looked easy, because the last one set a bar low enough to jump over blind.
And the mirror case, which I’ve also seen: a founder takes the biggest number on the table every time, because it feels like winning and because somebody always offers it. Two years later he’s not running a company anymore. He’s running a number. Every decision gets bent around defending a price he never should have accepted, for a business that hasn’t caught up to it yet, and may never.
Same market. Same access to capital. Opposite outcomes, and the difference was set before the company shipped anything.
The Move That’s Actually Happening
The disciplined founders might be leaving their ego at the door, but that doesn’t mean they’re leaving money on the table. They’re just collecting it later, at a better price.
Take the lower valuation. Go oversubscribed. Then sell some of your own stock into the excess demand. The investors who wanted in but didn’t get enough allocation come in at a materially higher price than the round itself, and the founder gets the discipline of an easy bar along with the liquidity of a rich one, in the same transaction.
I can’t help but laugh thinking about that famous scene from HBO’s Silicon Valley, “Why the f%^&* didn’t anyone tell me I could take less?!”:
This isn’t a clever trick a couple of founders stumbled into. Turner Novak and Hans Swildens have pointed out the secondaries market has gone from $250M to $150B over the last 25 years. That’s not an anomaly, that’s an entire structural release valve that’s been building for two and a half decades, and the smartest founders are finally the ones using it on purpose instead of by accident.
Why The Math Works Better This Way
Dan Gray at Odin has been writing the best version of the underlying argument: venture, like any organization, has a convex relationship between capital and outcome. Undercapitalized companies fail more. So do overcapitalized ones. The best outcomes cluster around optimally capitalized, not maximally capitalized.
Gray draws the parallel to private equity after 2008 — cheap capital and fee-driven scale ran ahead of actual performance until LPs revolted and forced real governance back into the system. He thinks venture is due for the same reckoning.
Zoom out further and the same story is already showing up in the data everyone’s citing: capital is concentrating hard at the very top of the fund market, LPs are quietly trimming venture allocation even while they keep writing checks, and pensions are posting better DPI in public markets than they are from traditional PE/VC. The asset class is being told the same thing the overpriced founder is being told. Scale and price are not the same thing as performance. Most of the system hasn’t priced that in yet.
The Obvious Rebuttal
Samir Kaji’s pushback: venture right now is a genuine supercycle and an obvious late-cycle bubble at the same time, and a portfolio that misses the one true outlier of the cycle can underperform just as badly as one that overpays for everything.
He’s not wrong. But that’s a portfolio-construction question: how many shots on goal, and how concentrated the fund should be. It’s a different question from whether an individual founder should price their own round at the top of the range just because someone will let them. You can believe in swinging for outliers and still believe the outlier shouldn’t be pricing themselves like they’ve already arrived.
The founders who understand the difference are the ones setting a bar they can actually clear, and getting paid for their patience later instead of pretending it isn’t a trade-off at all.
Valuation was never the outcome. Now, it’s looking more and more like it isn’t even the smart way to get paid.
See you Monday.